
Title Split Solicitors
Title Splitting
If you are looking to unlock the hidden value in your property portfolio, title splitting could be the key to maximising your investment returns. At Starck Uberoi, we specialise in providing expert legal services for title splitting, ensuring a smooth and profitable process for our clients.
A successful title split relies on the coordination of legal, finance, and tax strategies. That’s why, with recommended mortgage advisors, we offer a one stop title split solution.
Request a Callback
Your data is safe with us. Our friendly team is ready to answer your questions.
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.
Integrated Mortgage, Financial and Legal Solutions under one roof
What is a Title Split?
A title split involves dividing a larger property into multiple distinct units. For instance, if you plan to convert a
large house into separate flats for rental, you’ll need to carry out a title split and establish new leases for each
unit.
Title splitting can greatly enhance the value of your investment. By creating new leases rather than renting out the
entire property under a single freehold, you increase the property’s overall value and gain the flexibility to rent or
sell the individual leases for profit.
Why Might a Title Split Be a Good Idea for Me?
A title split can transform a property you don’t live in, into a long-term, high-yield investment instead of just
selling it. By converting a larger property into multiple units, you can sell or rent them out, increasing your
profits without needing to invest in multiple property acquisitions.
Title Split One Stop Shop
At Starck Uberoi, we don’t simply tell our clients what they should do – we actually do the work for you. Working with the help of recommended Mortgage Advisors allows us to provide a streamlined service.
No Upfront Fees
No Training Course Jargon

Qualified & Regulated Advisors
How can our one-stop shop help you?
A successful title split relies on the co-ordination of your mortgage application, your tax strategy and the creation of your leases; without this co-operation, there will be an imbalance between these three essential components which could cause delays and mistakes.
That’s what makes our integrated service so effective – by working with the help of recommended Mortgage Advisors, allowing us to provide a streamlined service.
Title Split Solicitors
We are title split experts, who can legally split your properties’ titles and create new leases to suit your needs from your investment.

Mortgage Advice
We can recommend you certified and recommended mortgage advisors. They will help you with the application process and meeting your lender’s requirements.
Tax Mitigation
Our combined approach enables us to help you keep your tax bill down, with personalised tax solutions on income tax, Stamp Duty and capital gains tax.
Our Title Split Team

Diana Lotfi

Gulben Uzum

Mehek Arora
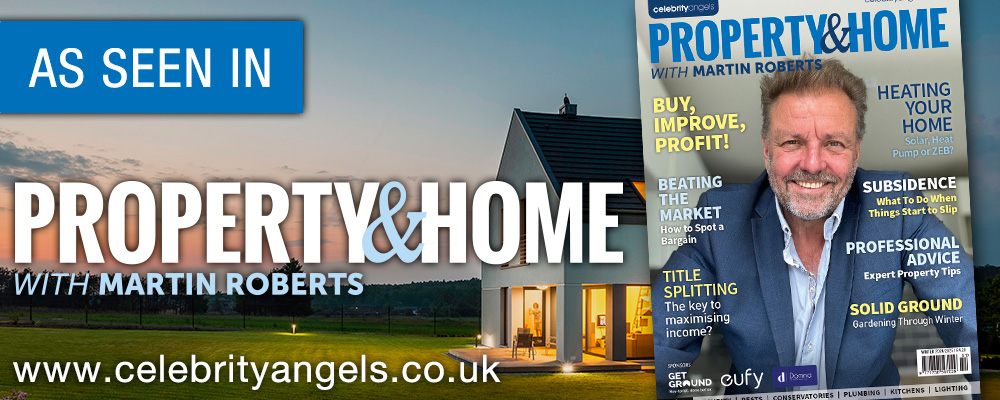
Our founder and Conveyancing Partner, Raminder Uberoi was featured in Property and Homes with this article.
What is a Title Split and How Can it Make You Money?
Read the web based version on Celebrity Angels
Title Splits: FAQ
Our solicitors and mortgage advisors receive numerous enquiries in relation to converting property into flats together with land registry title split. A common theme is a lack of understanding of the complex nature of SDLT and capital gains tax rules.
Here, are some Frequently Asked Questions our conveyancing solicitors encounter.
Will I need to create new leases for the converted properties?
You will need to split the title but you do not necessarily need new leases in order to rent out or sell your converted properties – however, you will need to grant new leases on your converted flats in order to sell them to a buyer who will be purchasing with a mortgage. Lease plans will be required to show information on boundaries, communal areas, parking and access to the garden.
How do I split my property's title deeds at the Land Registry?
The majority of property in the UK is recorded in the land registry, complete with the details of who owns what recorded in the property’s title. As a freehold owner of a property, you can split your property’s title into two or more and create leasehold titles.
The application to split your property’s title can be made at the land registry. There will be some conveyancing matters involved and you will need scale drawings of the intended flats. If you are granting new leases to the flats they will also need to be registered – these are all things our conveyancing solicitors can help with.
Can I be a freeholder and a leaseholder at the same time?
Generally, you cannot own both the leasehold and the freehold at the same time. If you wish to own a lease while retaining control over the freehold, you could transfer either the freehold or the lease into a third party’s name. Alternatively, you could set up a limited company and transfer either the lease or the freehold to this company.
Will I need planning permission to split my property into flats?
The land registry does not require you to have planning permission in order for you to split your property into multiple dwellings – however, your local council will likely require you to have full planning permission. There may also be pre-existing restrictive covenants existing on the title which may prevent certain developments from being made. Speak to your local planning authority about what will be required before commencing with any construction work.
Can I build additional storeys on top of my flats?
As of August 2021, property owners can build up to two additional storeys on top of their property without necessarily requiring full planning permission, in a bid to encourage the construction of more homes. This could be a great way to maximise rental income or sell more flats.
Can I split part of my garden?
Splitting property into flats isn’t the only way you can split your title – you may choose to split off some of your garden to be sold for development or even just to your neighbour. However, the process for doing this differs somewhat from splitting property into flats.
I want to convert and sub-divide my property into 2 separate self-contained flats and re-mortgage both leases at the same time as I split the title. Is this possible and will SDLT be payable on the re-mortgage of each flat? I want to convert and sub-divide my property into 2 separate self-contained flats and re-mortgage both leases at the same time as I split the title. Is this possible and will SDLT be payable on the re-mortgage of each flat?
Generally, a re-mortgage will not require SDLT to be payable because it is not a land transaction but the granting of new leases is a land transaction for SDLT purposes and SDLT may be payable. The amount of SDLT payable will be dependent on who the leases are granted to, i.e. an individual or a limited company, the value of the properties and the quantum of debt.
It is possible to split the title and re-mortgage at the same time rather than suffer the delay of having to wait for the land registry to register the separate leases and then being told by the new lender that the re-mortgages can only be completed 6 months after registration.
I am buying a freehold property with my son with view to take on a future development project and convert the property into 4 flats. My solicitor has advised me that leases cannot be granted to oneself so after we complete the flat conversion, we should grant the leases into a limited company owned by us. What is the SDLT implication in doing so?
SDLT will be payable on the price paid for the property.
If you subsequently convert the property to flats and grant the leases to a limited company, a further charge to SDLT will arise on the market value of the leases (regardless if no money is paid).There may also be CGT implications associated with this option.
The SDLT exposure could be reduced by granting the leases in your sole names (e.g. 2 flats in father’s name and 2 in son’s name) or to other individuals.
I own a freehold property with no mortgage worth £600k jointly with my wife and part of my retirement & inheritance planning is to split the title and grant 2 new leases into my wife’s sole name. Is SDLT and Capital Gains Tax payable?
Land transactions are exempt if there is no chargeable consideration. On the basis that your wife would not pay for the new leases, there would be no chargeable consideration and therefore no SDLT implications. This would not be the case if there was a mortgage on the property, as the assumption of debt by your wife would be treated as chargeable consideration for SDLT purposes (although the 3% surcharge does not apply in transactions between spouses/civil partners). Transactions between husband and wife/civil partners are treated as occurring at Nil Gain/Nil Loss for capital gains tax purposes. Therefore, no CGT would be payable on this transaction.
Transactions between other connected persons are treated as occurring at market value and therefore CGT could be payable if there is a gain attaching to the property in transactions which are not between spouses/civil partners.
I am looking to buy a property at auction which is advertised as split into 3 self-contained flats under one freehold title for £500k. I will finance the purchase with a bridging loan and subsequently plan to exit the bridge by granting 3 new leases to either my limited company or my adult children and to re-mortgage each flat with a high street lender. Will I end up paying SDLT twice i.e. firstly on the purchase and secondly on the grant of the 3 leases?
In this scenario, you do run the risk of having to pay stamp duty twice- once when you purchase the property and again when you grant the new leases. There are tax-efficient mechanics which can be used to avoid paying tax twice.
Whether you granted the leases into a limited company or into individuals’ names (in this case, into your children’s names), SDLT would be payable again because there is a “chargeable consideration” – something given in exchange. The release of the mortgage counts as chargeable consideration for these purposes.
However, if you can persuade the vendor to split the property into three leases for you to purchase instead and transfer the freehold separately, you would pay SDLT based on the combined value of the leases and you would be eligible for multiple dwellings relief. As a result, you’d only need to pay stamp duty once. Because the majority of the value would be taken from the freehold and put onto the leases, the value of the freehold will likely be too.
As with the case with any purchase made with bridging finance, you do need to ensure that you will be able to remortgage each flat in time to repay your bridging loan. Unlike regular high street lenders, bridging lenders are typically less lenient regarding repossession and will take action to repossess your property much quicker. Considering the current situation within the mortgage market, it may take longer than usual for you to arrange your new mortgages.
For this reason, you need to ensure your mortgage brokers and conveyancers are working quickly to get your new mortgages arranged in time – fortunately, our connection with Starck Uberoi Solicitors helps us ensure deadlines are met, so you won’t need to worry.
I own a freehold property worth £800,000 with an outstanding mortgage of £500,000. I divided the property into four flats 3 years ago and now want to split my title into three leases. I plan to remortgage the new leases to pay off the rest of my mortgage and raise more funds to purchase another property. Will this work and is SDLT payable?
This can work, but there’s a few things you’ll need to think about. A freeholder can’t grant leases to themselves, so you’ll need to grant the leases either to another individual or a limited company.
Bear in mind that SDLT is payable at the higher rate for companies for any leases worth more than £40,000, and the 15% corporate rate is applicable for properties worth more than £500,000. As mentioned above, SDLT on company property acquisitions is based on the market value of the property, rather than the price paid for it – so granting the leases for no premium won’t stop you from having to pay SDLT.
Regardless of who the “purchaser” is, there will also likely be a 3% surcharge applicable – this surcharge applies to all purchases by companies and to any purchases by individuals who already own at least one property and who aren’t replacing their main residence. On the plus side, you will likely be eligible for multiple dwellings relief, as explained above.
Mortgage Lender Panels
Trusted Residential Conveyancing
Related News and Legal Insights

Title Split
Selling Part of your Garden

Conveyancing, Property Solicitors, Title Split
Stamp Duty Land Tax (SDLT) and Flat Conversion

Bridging Loans, Conveyancing, Title Split
Bridging Loans for Property Development
Bridging Loans, Conveyancing, Property Solicitors, Title Split, Transfer Property to a Limited Company
Auction Conveyancing

Buy-to-Let, Conveyancing, Property Solicitors, Title Split, Transfer Property to a Limited Company
House in Multiple Occupation (HMO) Conveyancing

Title Split
Splitting Property into Two Titles


